EVs

Why the Combustion Engine Will Outlast the Electric Vehicle Hype — In Nigeria and Everywhere Else

By Hamisu Adamu Dandajeh

Electric vehicles (EVs) are often called “inevitable”. The only question, we’re told, is timing. Nevertheless, the data says otherwise. Even the world’s most electrified economies remain overwhelmingly combustion-powered on the road. Nigeria’s constraints run deeper still. They are not only rooted in physics, minerals and money, but also on political willpower.

Start with Norway. It is the closest thing the world has to a completed EV transition. Battery-electric vehicles made up 96–97% of new car sales in 2025. Decades of tax breaks, toll discounts and bus-lane access built that number. But look at the cars actually on Norwegian roads, not the ones sold this year. Only a third of the total fleet is electric. That is the highest share in the world. And it still leaves two-thirds of Norway’s cars running on combustion. Sales dominance and fleet electrification are not the same thing. That gap is the central fact of this entire debate.

Other countries make the point harder. China crossed 50% EV sales penetration in 2025. Its road fleet is still only about 13% electric. Germany’s EV sales share collapsed from 29% to 19% when subsidies were cut, then recovered to 28% once they returned. Adoption moves with subsidy, not momentum. The US sits at roughly 10% of new car sales, stalled since federal tax credits expired. Japan’s EV sales share fell from 3% to 2% in 2025.

Globally, the EV fleet reached about 116 million units in 2026. The world’s total car fleet exceeds one billion vehicles. China alone holds 61% of all EVs on earth. A 30% sales share this year still means a fleet penetration of five to seven per cent. Cars last fifteen to twenty years. Old stock does not disappear because new sales shift. This is steady progress. It is not imminent replacement.

Nigeria’s problem is a different category of constraint. The national grid serves over 220 million people. It generates between 4,000 and 4,800 megawatts on a good day. That is about 20 watts per person. Pakistan manages 180. Indonesia manages 250. The United States manages 3,530; 176 times Nigeria’s figure. You cannot charge an EV fleet on a grid that cannot keep the lights on. Nigeria’s grid still collapses outright. Generation crashed to 20 megawatts nationwide in January 2026.

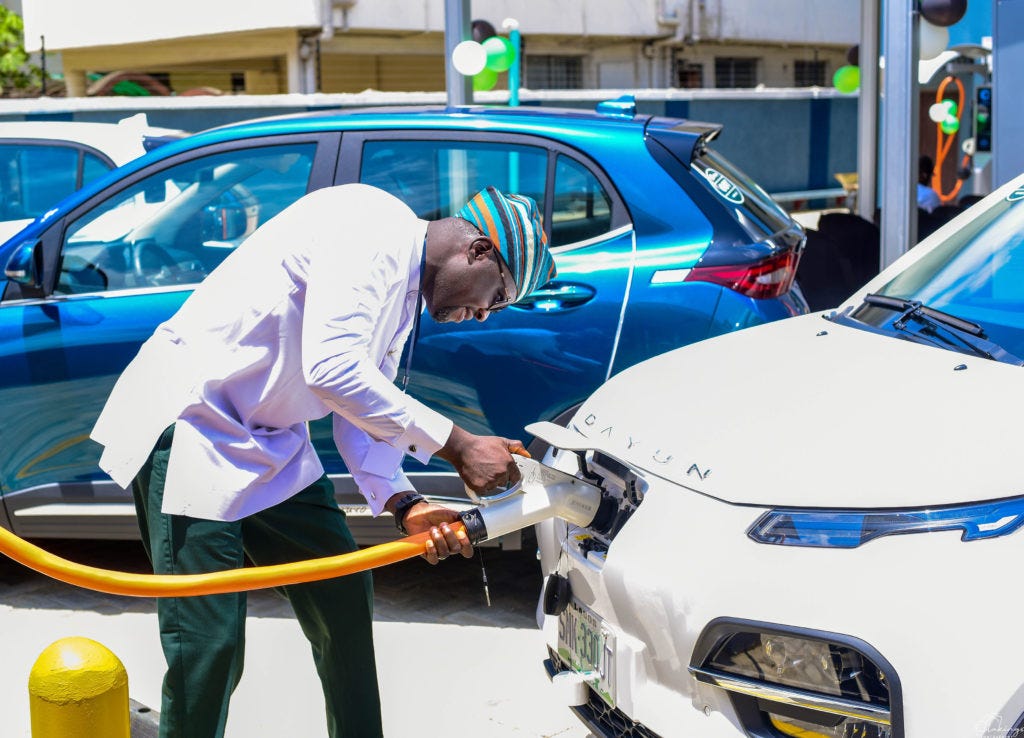
Nigeria’s Energy Transition Plan targets 60% EV fleet share by 2050. Today, EVs are under 1% of the country’s vehicles. That is a few tens of thousands of cars; by industry estimate, no official figure exists. Import duty waivers pushed nearly 4,000 more EVs into the country in the first half of 2026. They are landing in a market where the grid runs at 30% of installed capacity. Barely half the population has a grid connection at all. Public charging stations number around a dozen nationwide.

Here is the telling part. Nigerian charging operators now run diesel and petrol generators to keep their own chargers working when the grid fails. The EV system depends on the fuels it is meant to replace. A car charged from a diesel generator is not a clean-energy solution. It is a combustion engine with an expensive extension cord.

Electric two- and three-wheelers are the exception. They are gaining real ground, often paired with solar charging. They already beat petrol bikes on lifetime cost. But a solar-charged motorcycle and a grid-dependent passenger car are different problems. Confusing the two is where much of the optimism about Nigeria’s EV transition breaks down.

Four structural constraints hold the combustion engine in place even in wealthy, grid-secure economies. Minerals come first. The cobalt supply gap is projected to widen from 15% to over 25% by 2040. Lithium demand is set to more than triple. The real bottleneck is refining, not mining. China controls most of that capacity, regardless of where the ore comes from. Battery supply chains are nearly as exposed as the oil trade they aim to replace.

Grid capacity is the second constraint, and it is not just a developing-world problem. The US grid faces simultaneous demand growth from data centres, reshored industry, building electrification and EV charging. Data centre demand alone is forecast to more than double by 2035. Ninety per cent of US charging operators cite grid limits, not construction cost, as their biggest obstacle. Lagos and Chicago differ in degree, not in kind.

Fleet turnover is the third. Cars stay on the road for over a decade. Fleet electrification always lags sales electrification. Norway proves it: a third of its fleet is electric, compared with 97% of its sales. Even a Nigeria that hit 100% EV sales tomorrow would run a majority-combustion fleet well into the 2040s.

Heavy-duty transport is the fourth. Electric truck sales more than doubled in 2025. They still make up barely one in ten trucks sold worldwide, and mostly in China. Long-haul freight, shipping, aviation and heavy equipment remain unsolved. Battery energy density per kilogram still trails diesel and jet fuel by a wide margin. These are the vehicles moving most of the world’s freight.

None of this argues against electric vehicles. Norway’s numbers are real. China’s manufacturing scale is real. The direction of travel is toward more electrification. But “more” is not “complete replacement,” and only the first claim survives contact with the data.

Nigeria’s real constraint is a 4,000-megawatt grid serving a quarter-billion people. That leaves meaningful EV penetration limited, for now, to solar-charged two- and three-wheelers and isolated pilot fleets. The industrialised world faces a different but equally real constraint: a mineral supply chain that cannot yet support the scale being promised, a grid under pressure from EVs and data centres at once, and a vehicle stock so large that even a fully electrified sales market takes a decade or more to become a fully electrified road.

The honest forecast is not replacement. It is long, uneven coexistence. EVs will take a growing share of new sales where grids and supply chains allow it. Combustion engines will keep doing the heavy lifting for the existing fleet, and for the jobs battery technology still cannot do. Anyone promising a firm end date for the petrol or diesel engine is selling a story the numbers do not support.

Hamisu Adamu Dandajeh is an Associate Professor of Sustainable Fuels, Energy and Climate Change, Department of Mechanical Engineering, Ahmadu Bello University, Zaria, Nigeria. Email: hadandajeh@gmail.com

BUK Bans Charging of Private Electric Motorcycles on Campuses

By Muhammad Abubakar

The Management of Bayero University, Kano (BUK), has announced an immediate ban on the charging of privately owned electric motorcycles and other electric vehicles using the university’s electricity supply across all its campuses.

According to a special bulletin issued on Monday, the university said the widespread charging of private electric motorcycles has contributed significantly to rising electricity bills, placing a heavy financial burden on the institution.

The directive applies to staff, students, commercial motorcycle operators, and all other users of electric motorcycles. Management warned that anyone found violating the ban will face disciplinary action in line with the university’s rules and regulations.

The university has also directed Provosts, Deans, Directors, Heads of Departments, and Heads of Units to monitor compliance and report violations. In addition, a monitoring team will conduct regular patrols across the campuses to ensure strict enforcement of the directive.

BUK urged all affected persons to comply with the new policy, describing it as part of the university’s efforts to reduce energy costs and promote the prudent use of its resources.

Germany Offers Subsidy To New Electric Car Buyers

By Muhammad Abubakar

Germany’s new multi-billion-euro electric-vehicle subsidy program officially launched today, with the Federal Office for Economic Affairs and Export Control (BAFA) opening its digital application portal.

The initiative aims to revive domestic EV sales by offering private buyers between €1,500 and €6,000 in direct state funding. Under the new guidelines, fully electric vehicles are eligible for the maximum tier of support, while select plug-in hybrids can receive up to €4,500. Buyers can claim the subsidies retroactively for any qualifying vehicle registered on or after January 1, 2026.

Unlike previous incentive schemes, this program introduces strict social scaling based on household income. Individual buyers must have a taxable annual income under €80,000 to qualify, while the cap increases to €90,000 for families with two children.

The federal government has allocated a total of three billion euros to fund the initiative, which is projected to run through 2029 or until the budget is fully exhausted.

OPEC Sec Gen: Peak oil demand not on the horizon

By Haitham Al Ghais 

In the 1990s and 2000s, the world regularly saw column inches devoted to the theory of peak oil supply, amplified by voices like Colin Campbell and Matthew Simmons. Decades later, however, it has still not come to pass, as enhanced economics and constant improvement in technology have helped lower costs and open up new frontiers to expand the resource base.

The past decade or so has witnessed a shift to talk of peak oil demand, with some forecasters increasingly pushing theoretical scenarios that have decided before any data is analysed that oil should not be part of a sustainable energy future.

This is evident in some net zero scenarios, with suggestions that oil demand will peak before 2030 or, more dramatically, that oil demand will drop by more than 25% by 2030 and calls to stop investing in new oil projects. 

This narrative was repeated only yesterday when the IEA published its Oil 2024 report, which once again stated that oil demand would peak before 2030. It is a dangerous commentary, especially for consumers, and will only lead to energy volatility on a potentially unprecedented scale.

We have also heard similar narratives before, ones that have proven to be wrong. The IEA suggested that gasoline demand had peaked in 2019, but gasoline consumption hit record levels in 2023 and continues to rise this year. It also stated that coal demand had peaked in 2014, but today, coal consumption continues to hit record levels. 

Many net zero futures focus almost exclusively on replacing hydrocarbons, which make up more than 80% of the global energy mix today. Rather than adding new energy sources to the mix, the focus is on substituting energy sources, which flies in the face of the history of supplying energy to the world. The emphasis is on rhetoric over reality and constraint over consumer choice.

Today, wind and solar supply around 4% of global energy, with electric vehicles (EVs) having a total global penetration rate of between 2% and 3%, even though the world has invested over $9.5 trillion in ‘transitioning’ over the past two decades. OPEC welcomes all the progress made in renewables and EVs, but it is nowhere near close enough to replace 80% of the energy mix. Furthermore, electricity grids, battery manufacturing capacity and access to critical minerals remain major challenges. 

We should also remember that the development of renewables and EVs requires some oil-related products. Their future expansion will increase oil demand.

Of course, we all want to lower emissions, but at the same time, we all need ample, reliable and affordable supplies of energy. The two cannot be decoupled. Instead, our energy futures must focus on the full picture and not on a partial, incomplete one. In this respect, three key facts are worth bearing in mind. 

Firstly, future energy and oil demand growth primarily lies within the non-OECD developing world, driven by increasing populations, an expanding middle class and growing economies. From now until 2045, non-OECD oil demand is set to expand by over 25 million barrels a day (mb/d), with China and India contributing over 10 mb/d alone.

We should also remember that billions of people in the developing world still lack access to modern energy services. For these people, their energy future is not about net zero, deciding on the purchase of an electric vehicle, or ruminating over the costs and benefits of energy sources. Instead, it is about achieving the energy basics that the developed world takes for granted, such as being able to turn on a light, cook on a clean stove or have motorised transport to move to and from work or school.

Secondly, oil demand continues to increase. At OPEC, we see oil demand growth of 4 mb/d over the two years of 2024 and 2025, with other forecasters also seeing an expansion of over 3 mb/d. Even the IEA sees growth of 2 mb/d over this period, followed by growth of 0.8 mb/d in 2026. It then dramatically drops off a cliff to almost no growth in the next four years through 2030. 

This is an unrealistic scenario, one that would negatively impact economies across the world. It is simply a continuation of the IEA’s anti-oil narrative. Given the real trends we see today, we do not see peak oil demand by the end of the decade.

Thirdly, many parts of the world are witnessing consumer pushback as populations comprehend the implications of ambitious and unrealistic net zero policy agendas. This, in turn, is prompting policymakers to re-evaluate their approaches to future energy pathways, for example, in the UK, with the government recently supporting new oil and gas licenses. 

These shifts, alongside developments in the economic landscape, have seen OPEC revise its oil demand expectations upwards to 116 mb/d by 2045, and there is potential for this level to be even higher. We do not foresee a peak in oil demand in our long-term forecast.

On the supply side, technological improvements are allowing us to continually add resources to the base to help meet demand growth. There are clearly enough resources for this century and beyond, with the world’s proven crude oil reserves standing at over 1.55 trillion barrels. Moreover, technologies are also enabling us to take huge strides in reducing emissions, as exemplified by the availability of cleaner fuels, much-improved efficiencies and technologies such as carbon capture, utilisation and storage, carbon dioxide removal and direct air capture.

Everyone is free to have an opinion, but it is important that this is based on the realities we see before us today. There is a clear need to prioritise energy security, utilise all available energies, deliver energy affordability, enhance sustainability, reduce emissions, and not limit our energy options in the face of expanding demand.

Oil can deliver on all those fronts, and as we look to the future, its versatility ensures that we do not see peak oil demand on the horizon. Just as peak oil supply has never transpired, predictions of peak oil demand are following a similar trend.

Against this backdrop, stakeholders need to recognise the need for continued oil industry investment today, tomorrow, and many decades into the future, given the products derived from crude oil are essential for our daily lives. Those who dismiss this reality are sowing the seeds for future energy shortfalls and increased volatility and opening the door to a world where the gap between the ‘energy haves’ and ‘energy have-nots’ grows even further. 

Haitham Al Ghais became OPEC Secretary General in 2022. He served as Kuwait’s OPEC governor from 2017–21 and was the inaugural chairman of the OPEC+ Joint Technical Committee in 2017. Al Ghais was already an oil and gas industry veteran, having held senior positions in key OPEC and OPEC+ bodies and committees, as well as at the Kuwait Petroleum Corporation.