Economy

Ghana Launches Cedi-to-Yuan Payment System for Chinese Imports, Reducing Reliance on US Dollar

By Hadiza Abdulkadir 

Ghana has introduced a cedi-to-yuan payment system aimed at facilitating imports from China and reducing the country’s reliance on the US dollar for trade transactions.

Stanbic Bank Ghana is currently piloting the system, while Ghana Commercial Bank is developing a similar service, according to reports.

The new arrangement allows payments to be processed through China’s Cross-Border Interbank Payment System (CIPS), enabling direct yuan payments from cedi-denominated accounts.

By bypassing the need for US correspondent banks, the system is expected to cut transaction costs and shorten processing times for China-related trade.

The move marks a significant step in Ghana’s efforts to diversify its payment infrastructure and strengthen trade ties with China, its largest import partner.

Nigerian University Lecturers and the Self-Normalisation of Poverty

By Prof. Abdelghaffar Amoka Abdelmalik

I was invited to conduct an external examination for three postgraduate students (1 PhD and 2 MSc) at an institution about 87 kilometres from my university. The three theses were sent days before the scheduled examination for me to read page by page, contribute to improving the work, prepare questions, and then schedule a date to travel to examine the students.

I did not drive there.

I had an instinct that whatever mileage they would pay would not cover my fuel costs. I wasn’t prepared to spend my own money to finance an examination for which I had already done several days of intellectual work. You don’t want to know the honorarium for the several days of intellectual work.

So I took a bike to the park, boarded public transport, and travelled to the institution. To make the journey comfortable, I paid for two seats. The two seats cost ₦5,000. The examination lasted 6 hours without a break because it had to be concluded that day. At the end of the day, they brought me a claim to sign, and the mileage was ₦40 per kilometre. They quoted the distance to be 74 kilometres. That meant I was entitled to ₦2,960 for travelling to an institution approximately 87 kilometres away. That’s the worth we placed on ourselves. I laughed very hard, not because it was funny but because it was absurd and ridiculous.

Then, I asked them: So academics sat down and agreed that the cost of travelling one kilometre for a professor conducting a postgraduate external examination is ₦40? That was the moment I decided that this would be my first and last time honouring a postgraduate examination invitation from that institution.

I was lamenting this experience, and what I see as the self-normalisation of poverty in our universities, to a colleague. His response shocked me. He told me that, as a postgraduate coordinator, he does receive phone calls from senior colleagues asking to be considered for external examinations. They were not invited. They were calling to ask for the opportunity. That is when I began to think more deeply about self-normalisation of poverty.

Self-normalisation of poverty is the process by which people gradually begin to accept poverty, deprivation, and poor living conditions as normal, inevitable, or even acceptable. Poverty initially produces frustration. Prolonged poverty produces adaptation. Prolonged adaptation produces acceptance. And acceptance has eventually produced defence of the very conditions that created the poverty.

The danger is not merely that lecturers become poor. The greater danger is that poverty becomes normalised by the very people who should be challenging the conditions that produced it.

Meanwhile, I got an interesting response to my last piece from a professor who is proudly saving ₦500,000 per month. I must applaud the professor for sustaining his family and all his needs with an amount equivalent to the 2025 salary that ASUU thought was not enough for him. He was able to save from his pre-CATA salary, add it to the new CATA and professorial allowance, and save ₦500k every month. Seriously, saving ₦500,000 every month in Nigeria today is not a small achievement.

Within 2 years and with consistency, the professor will be able to save about ₦12 million, ignoring interest and unforeseen circumstances. But the reality is that the current value of that 10 million is about the same as the value of ₦700,000 that an Assistant Lecturer saved within 2 years from 2005 to 2007. A 15-year-old car that cost between ₦700 and ₦1m in 2007 costs about ₦10m now. 

So what exactly are we celebrating? The fact that a professor said he can now save ₦500,000 every month?

Or the fact that it takes a professor two years of disciplined saving to accumulate money whose purchasing power may resemble what a much more junior academic could accumulate much earlier?

For a lecturer celebrating a professor achieving in 2026, what an Assistant Lecturer could achieve in 2007 is a testament to the self-normalisation of poverty.

Let’s remember where we are coming from.

When I was employed in 2005, an Assistant Lecturer’s net salary was about ₦37,000. At the exchange rate of the time, that was roughly $280. In 2006, it rose to about ₦57,000, approximately $445. By 2009, during the Yar’Adua administration, the net salary of AL increased to around ₦110,000, approximately $738.

By 2022, ₦110,000 was worth only about $246 at the prevailing exchange rate. After subsidy removal in 2023 and naira devaluation, ₦110,000 dropped to as low as $73. By 2026, an Assistant Lecturer’s salary rose to roughly ₦250,000. That’s about $180. That is what we are celebrating. 

What happened to Nigerian professors? 

In March 2012, I purchased a London-Abuja British Airways round-trip ticket for £552.09 (₦138,574.59). In 2012, a professor’s salary was about ₦460,000 (£1,832.7). That means that by May 2015, a professor at the bar could afford a week’s holiday in London with his one-month salary. The ticket cost less than one third of the salary, and the remainder would comfortably cover the living expenses. 

From comfort to survival.

Since 2015, after Buhari came to power, the comfort that Obasanjo, Yar’Adua and Jonathan gave to university lecturers was taken away. Buhari’s 2022 strangulation of Academics is still very fresh. Then, Tinubu crushed that comfort in May 2023 (₦416,000, worth 277 USD for a professor at the bar) by withdrawing fuel subsidies and devaluing the naira, before a raise in 2026 to about ₦1m (750 USD) for a professor. But the value is still less than what Buhari left it at: ₦416,000 (930 USD) for a professor at the bar.

The Stalin Chicken. 

This is where the Joseph Stalin-Chicken metaphor becomes powerful. A chicken is being plucked. It is painful. It is losing its feathers. It has nowhere to go. Then the same hand that has been plucking its feathers throws a few grains of food in front of it. The chicken follows the hand.

Not because the hand has stopped hurting it. But because survival has become more important than resistance.

That is what poverty can do to human beings. It can make people grateful for crumbs from the very system whose structure has impoverished them. And I fear that some academics have become so desperate for survival that they follow the very hand that has caused their suffering, simply because that hand is now offering them crumbs.

The application of the Stalin Chicken model, especially on academics, is a brilliant one from PBAT.

I will excuse those relatively young academics who do not know where we are coming from. They cannot compare what they have with what existed before they entered the system.

Of course, we are grateful to God for our current situations. We should also be grateful for the improvements that have occurred. But gratitude should not kill critical thinking. Real academics are not supposed to become professional worshippers of crumbs. We should interrogate systems. We should ask questions. We should challenge policies. We should understand the difference between survival and progress.

However, as more senior academics mobilise for endorsement, don’t go in with self-normalised poverty in academia. Ensure that you negotiate for an endorsement package that can at least change your car. Don’t go for crumbs.

Best wishes!

Cashew Association Targets 1 Million Metric Tonnes Annual Production In 10 Years

By Sabiu Abdullahi

The National Cashew Association of Nigeria (NCAN) has announced plans to increase the country’s annual cashew production from about 300,000 metric tonnes to 1 million metric tonnes within the next 10 years.

The association’s president, Ademola Adesokan, revealed the target during the inauguration of NCAN’s national and state executives at the Federal Ministry of Industry, Trade and Investment (FMITI) in Abuja.

Adesokan said the association also aims to process at least half of the projected 1 million metric tonnes within Nigeria. He explained that the initiative is supported by a well-defined implementation strategy.

According to him, the roadmap will promote industrialisation, expand non-oil exports, attract investment and create employment opportunities across the country’s cashew-producing states.

He stressed that state chapters would play a central role in achieving the targets because production activities take place at the grassroots.

> “Policy is written in Abuja, but cashew is grown, harvested, dried, aggregated, and stored in our states — in our farming communities, our warehouses, our local markets. The National Cashew Roadmap can only succeed if it has strong hands to carry it at the grassroots. That is why state chapters are not a formality. They are the engine room of this entire transformation.


“The quality of the nuts that reach our processors, the integrity of our storage systems, the efficiency of our aggregation networks — these do not happen in a ministry office. They happen because of the men and women in this room today, and the chapters you now lead.


“When a processor in Kogi or an exporter in Lagos can trust the quality of what comes through our supply chain, it is because a state chapter somewhere insisted on doing it right. That is industrial development at the grassroots — real, measurable, and yours to own,” he said.


The Federal Ministry of Industry, Trade and Investment also reaffirmed its commitment to supporting the cashew sector. The ministry described the inauguration of the association’s executives as an important milestone in the implementation of the recently validated Nigeria Cashew Roadmap.

The Director of the ministry’s Industrial Development Department, Olumuyiwa Jayi-Ade, spoke through Assistant Director Popoola Abimbola. He said the inauguration signalled the beginning of the roadmap’s implementation phase after the completion of policy development.

He praised NCAN for its role in developing and validating the Nigeria Cashew Roadmap. He said the association had established a strong foundation for a sustainable and globally competitive cashew industry.

Jayi-Ade added that the ministry would work with the Federal Ministry of Agriculture and Food Security, NCAN and development partners to prepare implementation plans and institutional frameworks for the roadmap.

He also disclosed that the Nigerian Cashew Project Office (NCPO) would be established to coordinate reforms, strengthen collaboration among stakeholders and supervise the implementation of programmes across the cashew value chain.

Financing Hope: Waqf Sukuk for Northern Nigeria’s Displaced Communities

Dr Auwal Adam Sa’ad

Northern Nigeria stands at a defining moment in its humanitarian and development history. Years of insurgency, armed conflict, banditry, communal violence, and environmental shocks have displaced millions of people from their homes. Women and children bear the greatest burden of this crisis. Many now live in internally displaced persons (IDP) camps or host communities where access to education, healthcare, housing, livelihoods, and economic opportunities remains severely constrained.

For years, humanitarian agencies, governments, charitable organisations, and development partners have provided emergency assistance that has undoubtedly saved lives. Food distribution, temporary shelter, healthcare interventions, and emergency education programmes have prevented an even greater catastrophe.

Yet an uncomfortable reality remains: emergency aid cannot become a permanent development strategy.

Humanitarian assistance addresses immediate needs but seldom creates enduring economic resilience. Once donor funding ends, many beneficiaries remain trapped in poverty and dependence. The cycle of vulnerability simply begins again.

Northern Nigeria therefore requires a financing model that moves beyond relief towards sustainable empowerment. One promising solution lies within the rich heritage of Islamic social finance: the integration of Waqf and Sukuk into a single development instrument known as Waqf Sukuk.

For centuries, Waqf has served as one of Islam’s most powerful institutions for public welfare. Across the Muslim world, endowed assets financed universities, hospitals, roads, water systems, orphanages, and social services that continued serving communities long after their founders had passed away. Waqf created permanent social infrastructure because its assets remained intact while only their benefits were utilised.

Sukuk, meanwhile, have become one of the fastest-growing segments of global Islamic finance. Unlike conventional bonds, Sukuk represent ownership interests in tangible assets or productive ventures that comply with Shariah principles. Today, governments and corporations worldwide use Sukuk to finance infrastructure, transportation, renewable energy, housing, healthcare, and industrial development.

Sukuk, meanwhile, have become one of the fastest-growing segments of global Islamic finance. Unlike conventional bonds, Sukuk represent ownership interests in tangible assets or productive ventures that comply with Shariah principles. Today, governments and corporations worldwide use Sukuk to finance infrastructure, transportation, renewable energy, housing, healthcare, and industrial development. Nigeria’s own experience demonstrates the remarkable market confidence in this ethical financing instrument.

The Federal Government’s Series VII Sovereign Sukuk recorded an unprecedented subscription of over ₦2.205 trillion—an oversubscription of approximately 735 per cent—underscoring the enormous investor appetite for transparent, asset-backed, and socially impactful investments. The combination of this strong investor demand with the enduring social mission of Waqf creates an extraordinary opportunity. The combination of these two institutions creates an extraordinary opportunity.

A Waqf Sukuk mobilises investment capital to establish productive assets that are permanently dedicated to charitable purposes. Instead of distributing donated funds until they are exhausted, the proceeds finance income-generating projects whose revenues continuously support vulnerable populations.For Northern Nigeria, this could fundamentally reshape humanitarian financing.

Rather than repeatedly financing food distribution, Waqf Sukuk could establish agricultural processing facilities owned by Waqf institutions that employ displaced women while generating revenues for education and healthcare programmes.

Instead of constructing temporary shelters that require constant maintenance funding, Waqf Sukuk could finance affordable housing developments whose rental income supports social services.

Vocational training centres, healthcare clinics, women-owned cooperatives, renewable energy projects, irrigation schemes, commercial markets, educational institutions, and microfinance programmes could all become endowed assets whose earnings are perpetually reinvested into community development.This is not charity that ends with consumption.It is charity that continuously reproduces itself.And the economic implications are profound.

Every naira invested through Waqf Sukuk becomes a productive asset capable of generating recurring benefits for decades. Beneficiaries are no longer viewed merely as recipients of aid but as active participants in economic production. Skills development replaces dependency. Enterprise replaces vulnerability. Opportunity replaces uncertainty.

This model also reflects the higher objectives of Islamic law (Maqasid al-Shariah). It protects life by improving healthcare and food security. It preserves intellect through education and vocational training. It safeguards wealth by creating sustainable livelihoods. It protects families through decent housing and social welfare. Above all, it restores human dignity by enabling displaced persons to rebuild their own futures.

The relevance of Waqf Sukuk extends beyond religious ideals. It strongly complements the United Nations Sustainable Development Goals, particularly those relating to poverty eradication, quality education, gender equality, decent work, reduced inequalities, sustainable communities, and partnerships for development.Its appeal therefore reaches multiple stakeholders.

For Northern Nigerian society, Waqf Sukuk revives a deeply respected Islamic tradition of community solidarity while adapting it to contemporary development challenges. It demonstrates that Islamic finance is not merely a commercial enterprise but also a powerful instrument for inclusive social transformation.

For wealthy individuals and philanthropists, Waqf Sukuk offers an opportunity to create perpetual charitable impact rather than one-time donations. Their contributions become lasting investments in human development that continue generating rewards both socially and spiritually.

For corporations, participation strengthens corporate social responsibility and environmental, social, and governance (ESG) commitments. Supporting Waqf Sukuk enables businesses to contribute directly to regional stability, workforce development, poverty reduction, and economic inclusion while enhancing their public reputation as responsible corporate citizens.

For investors, Waqf Sukuk represents an ethical investment vehicle backed by tangible assets and measurable social outcomes. The growing global demand for impact investing suggests considerable interest among investors seeking opportunities that combine financial discipline with meaningful developmental impact.

International development partners should likewise recognise the strategic importance of this model. Around the world, humanitarian agencies increasingly acknowledge that aid dependency cannot continue indefinitely. Innovative financing mechanisms are becoming central to sustainable development policy.

Waqf Sukuk offers exactly such an innovation. It complements humanitarian programmes rather than replacing them. Emergency assistance remains indispensable during crises, but Waqf Sukuk creates the permanent institutions that reduce dependence on future aid by building local economic capacity.

Countries such as Malaysia, Indonesia, Türkiye, and several Gulf states have already demonstrated the growing potential of integrating Islamic social finance with national development priorities. Nigeria possesses every ingredient necessary to become Africa’s leading centre for socially oriented Islamic finance.

However, successful implementation requires robust policy support. Federal and state governments should establish comprehensive legal frameworks governing Waqf assets, Sukuk issuance, governance standards, transparency, beneficiary protection, auditing, and performance reporting. Regulatory certainty will significantly improve investor confidence.

Tax incentives can encourage private participation. Public-private partnerships can leverage government support with private investment. Islamic financial institutions should develop specialised Waqf Sukuk products tailored to humanitarian and development objectives. Universities and research institutions should contribute through policy research, professional training, and impact assessment. Traditional institutions, religious leaders, and civil society organisations should mobilise public awareness to build trust and acceptance.

Development finance institutions and multilateral organisations can further strengthen the ecosystem through technical assistance, credit enhancement mechanisms, capacity building, and co-financing arrangements.The humanitarian crisis in Northern Nigeria demands solutions that are as enduring as the challenges themselves.

Emergency aid will always have an important place during periods of crisis. But rebuilding societies requires more than relief. It requires institutions that continuously generate hope, opportunity, and economic independence.

Waqf Sukuk represents precisely such an institution. It transforms generosity into productive capital, compassion into sustainable investment, and charity into perpetual empowerment. It reflects both the ethical foundations of Islamic finance and the practical realities of modern development economics.

The displaced women and children of Northern Nigeria deserve more than temporary survival. They deserve access to education, productive employment, dignified housing, quality healthcare, entrepreneurship, and the opportunity to shape their own futures.

Waqf Sukuk offers a pathway towards that future. Its widespread adoption by governments, corporations, investors, philanthropic organisations, Islamic financial institutions, and international development partners could redefine humanitarian financing in Nigeria and establish a model worthy of replication across Africa.

The question is no longer whether we can afford to innovate.It is whether we can afford not to.

Auwal is an associate professor at the Institute of Islamic Banking and Finance, IIUM. He can be reached via: auwal@iium.edu.my.
CBN Chooses Stability Over Risk as Global Uncertainty Persists

By Salmanu Isah


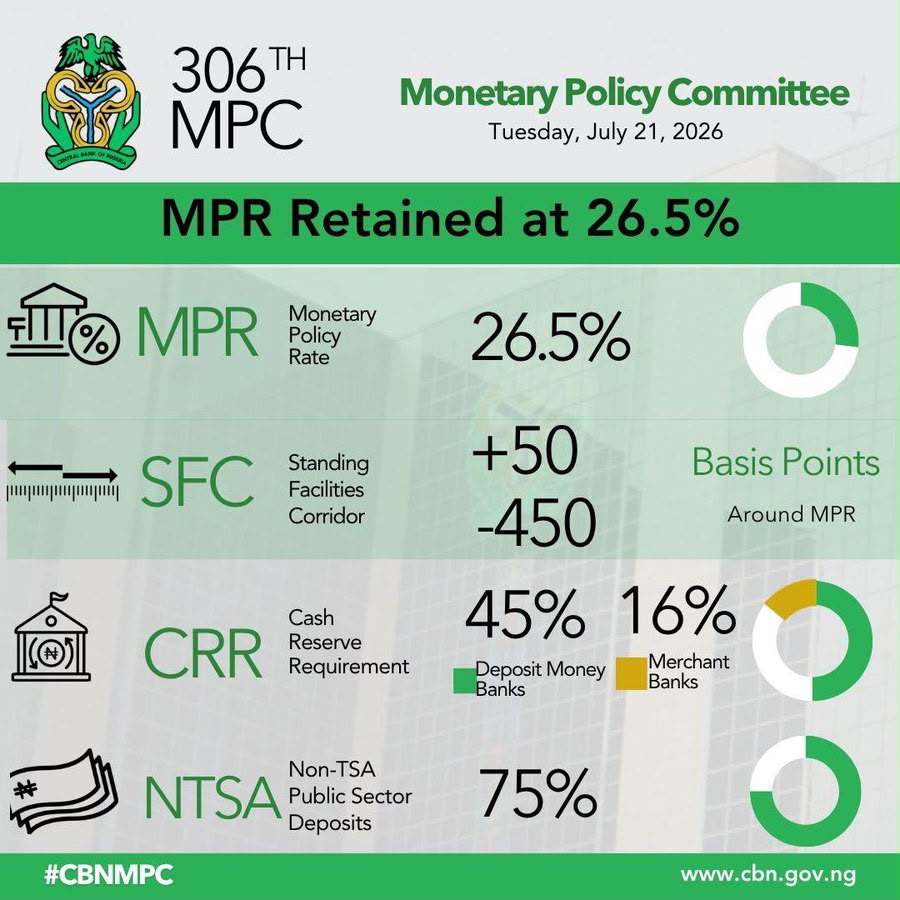
The Central Bank of Nigeria (CBN) has once again demonstrated its preference for caution and stability, opting to retain the Monetary Policy Rate (MPR) at 26.5 per cent despite a gradual easing of inflationary pressures across the country.


At the end of its 306th Monetary Policy Committee (MPC) meeting, the apex bank resisted calls for an immediate adjustment to interest rates, choosing instead to hold all major monetary policy parameters steady. The decision reflects the CBN’s determination to protect the progress made in stabilising the economy while remaining vigilant against fresh threats emerging from the global environment.


For the CBN, the modest decline in inflation is encouraging but not yet sufficient to justify a policy shift. Although headline inflation eased slightly in June and core inflation recorded a more noticeable drop, policymakers remain concerned that renewed tensions in the Middle East could trigger another wave of global price increases, particularly in energy and food markets. Such developments would inevitably have consequences for Nigeria, where imported inflation continues to influence domestic prices.


The Bank’s decision signals confidence in the effectiveness of its previous policy actions. Over the past two years, the CBN has maintained a firm anti-inflation stance, tightening monetary conditions and implementing reforms aimed at restoring confidence in the foreign exchange market. The latest economic indicators suggest that some of these measures are beginning to deliver results.


Exchange rate stability has improved considerably compared to previous periods, helping to reduce pressure on prices. External reserves have also strengthened, rising above $52 billion, providing a significant buffer against external shocks and reinforcing investor confidence in the economy. These developments have given the CBN greater room to maintain its current course while carefully monitoring future trends.


Beyond inflation, the MPC’s statement highlights the growing importance of collaboration between the CBN and the Federal Government. The Committee acknowledged that recent coordination between fiscal and monetary authorities has helped cushion the domestic economy from global disruptions. This recognition reflects a broader understanding that sustainable economic stability cannot be achieved through monetary policy alone.


While the CBN continues to focus on price and financial system stability, the government is expected to complement these efforts through reforms that boost productivity, improve infrastructure, increase oil production and diversify revenue sources. The Committee’s endorsement of ongoing reforms in the oil and solid minerals sectors underscores the need for broader economic transformation beyond monetary interventions.


The banking sector also emerged as a bright spot in the MPC’s assessment. The Committee expressed satisfaction with the progress of the banking recapitalisation exercise, describing it as a significant step towards strengthening the resilience of financial institutions. A stronger banking system not only enhances financial stability but also positions banks to support economic growth through increased lending and investment.


Despite a slight slowdown in economic growth during the first quarter of 2026, signs of resilience remain visible. The non-oil sector continues to drive economic activity, supported by telecommunications, financial services, transportation and trade. The return of the Purchasing Managers’ Index to expansion territory further suggests that business confidence may be gradually improving.


Looking ahead, the CBN appears cautiously optimistic. Inflation is expected to moderate further as the effects of previous monetary tightening continue to filter through the economy and food supplies improve during the harvest season. However, policymakers are clearly unwilling to declare victory too early. The possibility of a prolonged conflict in the Middle East remains a major concern, with the potential to disrupt global markets and reignite inflationary pressures.


Ultimately, the CBN’s latest decision reflects a central bank focused on protecting hard-earned gains rather than pursuing quick wins. By holding rates steady, the Bank is sending a message that economic stability remains its overriding objective. For businesses, investors and households alike, the decision provides a measure of predictability at a time when uncertainty continues to dominate the global economic landscape.


As Nigeria navigates both domestic challenges and external risks, the CBN’s cautious approach suggests that maintaining stability will remain more important than pursuing aggressive policy changes in the months ahead.


Salmanu Isah Darazo is a publisher and policy analyst. He can be reached via Salmanudrz@gmail.com

Cooking Gas Prices Decline Across Parts of Nigeria

By Sabiu Abdullahi

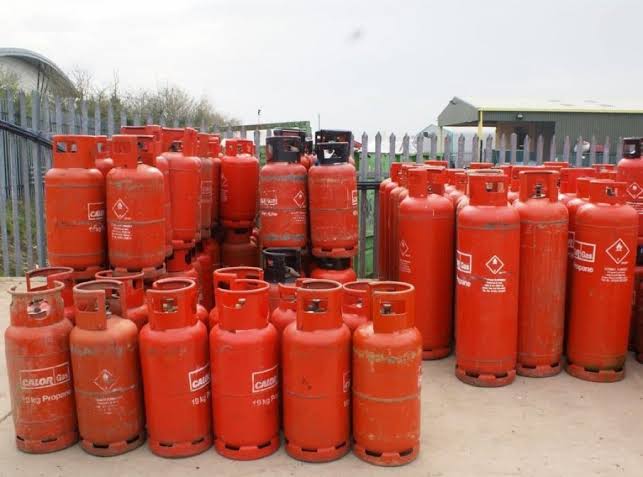
The cost of liquefied petroleum gas, popularly known as cooking gas, has started dropping in several parts of Nigeria after weeks of price increases linked to supply shortages.

Findings at some cooking gas outlets in Abuja showed that the product now sells between N1,450 and N1,500 per kilogram at stations operated by AA Shafa and Ranoil in areas such as Dutse and Gwarimpa.

Retail outlets in Kubwa, Dawaki, Bwari, Lugbe and other parts of the Federal Capital Territory were also found to be selling cooking gas between N1,650 and N1,700 per kilogram, depending on the location. The prices had earlier climbed to about N2,000 per kilogram in some areas.

The latest development indicates that cooking gas prices have dropped by between N200 and N350 per kilogram in recent weeks.

Checks further revealed that depot owners currently sell LPG between N1,065 and N1,100 per litre for a kilogram.

Despite the recent reduction, the price of cooking gas remains higher than the N1,000 to N1,200 range recorded before May 27, 2026.

Industry operators had earlier called for an increase in LPG imports to improve supply across the country.

Spokespersons of the Oil and Gas Suppliers Association of Nigeria, NOGASA, and Nigerian Independent Petroleum Company Plc, NIPCO, Chinedu Ukadike and Taofeek Lawal, attributed the earlier increase in cooking gas prices to seasonal factors, rising demand and supply shortages.

Women Need Better Access to Credit

By Jamiu Abdulgafar Olamilekan

The Punch Newspaper editorial on May 5, 2026 (Page 18), titled “Women Need Better Access to Credit”, highlights one of Nigeria’s most persistent economic blind spots. Despite their immense contributions to business, agriculture, trade, and family welfare, women remain locked out of the financial support they need to grow and thrive.

Across Nigerian markets, women dominate petty trading and small-scale enterprises from fashion shops and food businesses to salons, online ventures, and farming. Yet, securing loans from banks is often impossible.

As the editorial points out, collateral requirements, guarantors, and complex documentation create barriers that many hardworking women in both rural and urban communities cannot overcome.

This exclusion is, to say the least, unjust. Women are among the most financially responsible members of society, stretching limited resources to support children, families, and entire communities. Still, government empowerment programmes frequently fail to reach them.

In some cases, corruption, favouritism, and poor implementation dilute their impact, while lack of financial education and weak communication leave rural women unaware of opportunities that could change their lives.

Going forward, banks and other financial institutions must design loan systems that are flexible and inclusive. Lower interest rates for female-owned small businesses, coupled with expanded financial literacy programmes, would ensure women not only access credit but also manage it effectively.

The government, on its part, must enforce transparency and accountability in policies aimed at empowering women.

Beyond economics, financial empowerment strengthens families and reduces poverty. A woman with a stable income is more likely to invest in education, healthcare, and better living conditions for her household. The ripple effect benefits society at large.

Nigeria cannot claim to pursue inclusive growth while millions of women remain financially excluded. Empowering women is not charity — it is a strategic investment in the nation’s future.

Jamiu Abdulgafar Olamilekan is a Strategic Communication student at Yakubu Gowon University, Abuja. He can be reached at jamiuabdulgafar510@gmail.com.

Borrowing and National Development: Lessons for Nigeria

By Rahab Abashi

Debt has emerged as one of the most contentious topics in Nigeria today. Public opinion is often divided, as many view borrowing as an inherent evil, while others argue it is a necessary tool for development. 

In my view, borrowing is not inherently detrimental; rather, the crux lies in how these funds are utilised and whether they effectively stimulate national growth.

Many of the world’s most powerful economies operate on significant debt. Global leaders such as the United States, Japan, China, the United Kingdom, France, Germany, India, Italy, Canada, and Brazil all carry substantial national burdens. 

The United States owes over $34 trillion, Japan’s debt exceeds $9 trillion, and China’s stands at more than $14 trillion. Similarly, developed nations like the United Kingdom, France, and Italy owe trillions of dollars. 

Despite these figures, these nations maintain robust economies by channelling borrowed capital into high-impact sectors such as industry, technology, infrastructure, and commerce.

A defining characteristic of these successful nations is their diversified revenue streams. The United States generates wealth through technology, entertainment, finance, and manufacturing. China dominates in production and exports, while Germany is a global leader in engineering and automobiles. 

India, meanwhile, earns significantly from software services and its world-renowned film industry, Bollywood. While these countries borrow, they possess resilient systems that generate the income necessary to service and repay those loans without seriously impacting citizens.

Nigeria’s predicament is notably different due to an over-reliance on a single commodity. Crude oil remains the nation’s primary source of revenue and foreign exchange. 

Consequently, whenever global oil prices fluctuate, the Nigerian economy suffers a direct hit. This volatility highlights the inherent risk of a mono-product economy, particularly for a country with Nigeria’s massive population.

I believe that borrowing itself is not the primary issue. The real challenges are poor management and a lack of economic diversification. If Nigeria secures loans to revitalise electricity, transportation, agriculture, education, and healthcare, debt becomes a catalyst for development. 

However, when borrowed funds are mismanaged or fail to improve the standard of living, debt is understandably perceived as a burden.

Beyond oil, Nigeria possesses several sectors with immense revenue potential. Agriculture is paramount, given our fertile land and large workforce; the country could achieve significant gains from exports of rice, cocoa, cassava, and palm oil. 

Our entertainment industry is expanding rapidly, with Nigerian music, film, comedy, and fashion gaining global acclaim. Technology also offers a bright frontier, as Nigerian youth increasingly excel in digital skills, software development, and innovation.

With this potential left to stagnate, Nigeria must pivot toward developing a multi-sectoral economy. Economically successful nations are rarely dependent on a single source of income. 

Borrowing is a viable strategy provided the capital is invested wisely in productive sectors that drive growth and create jobs. 

If the giant of Africa prioritises investment in agriculture, entertainment, technology, manufacturing, and tourism, it can build a resilient economy and finally break its precarious dependence on oil.

Abashi Rahab is a student of Strategic Communication at Yakubu Gowon University, Abuja.  An intern with IMPR.  She can be reached at: abashirahab@gmail.com.

Quila Birds Trigger Food Security Fears Among Kebbi Rice Farmers

By Dahiru Kasimu Adamu

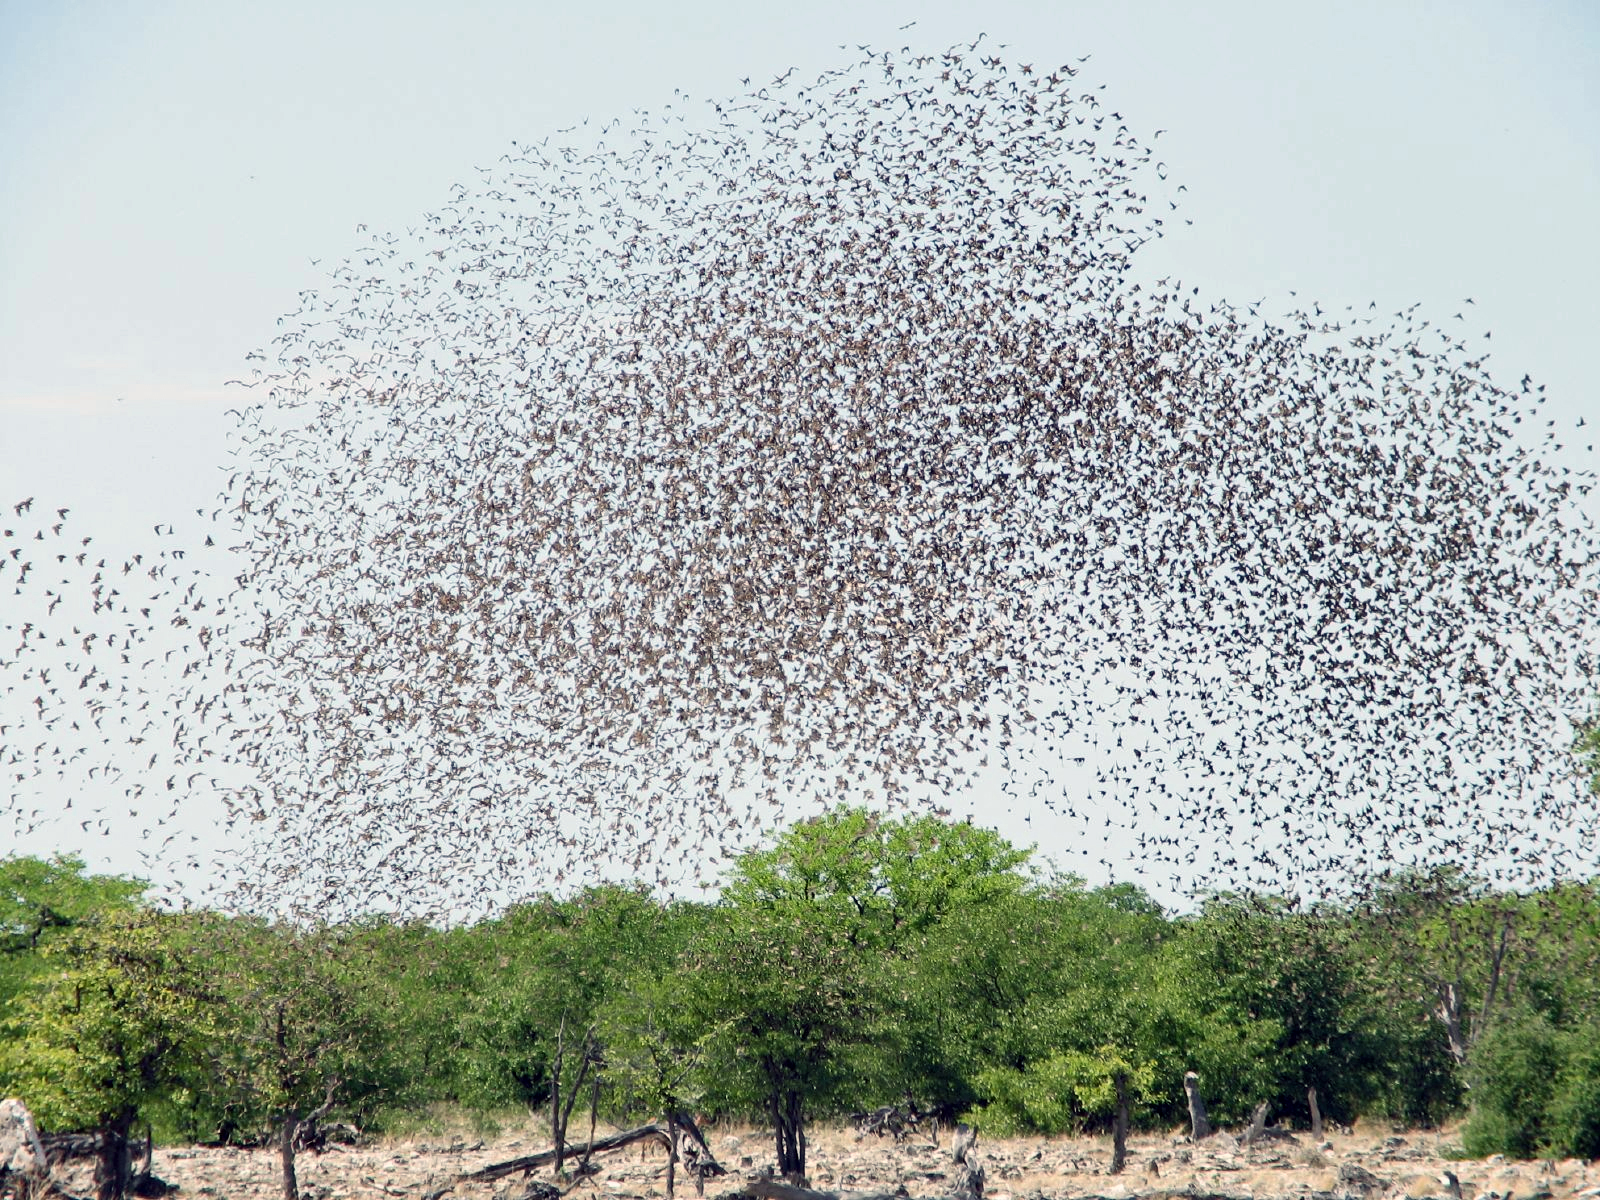
Rice farmers in Kebbi State are in a dilemma as quila birds, locally known as Buwa, continue to threaten food security by devouring their farm produce.

During a visit to rice clusters in the Argungu fadama land, including Dankwalli, Kuyar Masama, Janduma, Kwalaga, and others, farmers were seen shouting, wielding sticks, and using other materials to make loud noises to scare the birds away from their farms.

The farmers described the situation as disastrous. “Quila birds need only a short time to finish what farmers spend months cultivating. This forces us to move early to the farms and prevent the birds from ending our farming,” said Lauwali Usman, a farmer at the Dankwalli rice cluster.

Another farmer, Usman in Kuyar Masama,  explained how the quila bird “has caused some farmers to harvest their rice early because they can no longer keep moving to their farms every morning and evening to prevent the birds from eating their produce. They are afraid of losing what they spent months cultivating.”

Many farmers have stories to tell about the quila bird and how it threatens rice farming. What they share in common, however, is an appeal to authorities to assist them by spreading chemicals to eliminate the birds, arguing that traditional methods are too weak.

In a previous interview, Dr Aminu Aliyu, an agriculturalist who teaches at the Department of Agricultural Education, Adamu Augie College of Education, Argungu, said the best and most scientific method of addressing the quila bird problem is “locating their nesting environment and spreading chemicals. This can be achieved by collaborating with local farmers and extension agents, and is normally done by the state government or in conjunction with the federal government.”

Dr Aliyu described quila birds as “migratory birds that travel long distances and can cause havoc to any farm they stay on, even within a short period.”

Apart from rising input costs and the petrol price hike due to subsidy removal, the quila bird has been a major problem affecting rice farmers since the beginning of dry season farming, known locally as Katashi in Kebbi State.

CBN Holds the Line: What the 26.5% Interest Rate Means for Nigerians

By Salmanu Isah Darazo

The decision by the Central Bank of Nigeria to retain the Monetary Policy Rate (MPR) at 26.5 per cent reflects a carefully calibrated policy direction aimed at balancing inflation control, exchange rate stability and economic growth amid mounting global uncertainties.

At the end of its 305th Monetary Policy Committee (MPC) meeting held on May 19 and 20, 2026, the apex bank chose to maintain all key monetary parameters, signaling a continuation of its tight monetary policy stance despite moderating inflation indicators and improving macroeconomic fundamentals.

The decision comes at a time when Nigeria’s economy is navigating both domestic recovery and external shocks arising from geopolitical tensions, particularly the ongoing Middle East crisis, which has triggered increases in global energy prices and logistics costs.

For policymakers at the Central Bank of Nigeria, the challenge is not merely reducing inflation, but ensuring that the gains achieved through recent economic reforms are not reversed by premature policy loosening.

Inflation Still the Primary Concern

Although headline inflation rose marginally from 15.38 per cent in March to 15.69 per cent in April 2026, the MPC viewed the increase as temporary and largely imported. Food inflation climbed to 16.06 per cent due to rising transportation and logistics costs, while core inflation moderated to 15.86 per cent.

More significantly, month-on-month inflation slowed sharply to 2.13 per cent from 4.18 per cent, while the 12-month average inflation rate declined for the sixth consecutive month.

These indicators suggest that the aggressive monetary tightening pursued by the Central Bank of Nigeria over the past two years is gradually yielding results.

However, the MPC’s decision to hold rates rather than begin easing indicates that the apex bank remains cautious about declaring victory over inflation too early. Monetary authorities appear concerned that loosening rates prematurely could reignite inflationary pressures, weaken investor confidence and place renewed strain on the foreign exchange market.

By retaining the benchmark rate, the Central Bank of Nigeria is attempting to anchor inflation expectations while preserving confidence in the broader macroeconomic framework.

Reform Gains Influencing Monetary Confidence

A key message from the MPC meeting is that Nigeria’s recent policy reforms are beginning to strengthen economic resilience.

The committee repeatedly referenced exchange rate stability, stronger external reserves, improved monetary policy transmission and fiscal consolidation as evidence that the economy is better positioned to withstand external shocks than in previous years.

Gross external reserves increased to $49.49 billion as of mid-May 2026, enough to cover more than nine months of imports. This represents a major buffer against exchange rate volatility and external market pressures.

The committee also highlighted the successful completion of the banking recapitalisation exercise, which produced 33 stronger and better-capitalised banks capable of supporting economic growth and financial stability.

Taken together, these developments appear to have reinforced the confidence of the Central Bank of Nigeria in maintaining a steady policy stance rather than resorting to emergency tightening measures.

Growth Versus Tight Monetary Policy

One of the recurring criticisms of high interest rates is their impact on private sector borrowing, investment and overall economic growth.

At 26.5 per cent, Nigeria’s benchmark interest rate remains one of the highest in Africa, raising concerns among manufacturers and businesses about the cost of credit.

Nevertheless, recent economic data suggest that growth has remained relatively resilient despite the tight monetary environment. Nigeria’s economy expanded by 4.07 per cent in the fourth quarter of 2025, supported by growth in agriculture, industry and services sectors.

The oil sector also recorded stronger performance due to improved refining activities.

For the MPC, these growth figures may have strengthened the argument that the economy can still withstand elevated interest rates while inflation is being brought under control.

This reflects the classic central banking dilemma: tightening monetary policy may slow borrowing and spending in the short term, but policymakers believe such measures are necessary to restore long-term macroeconomic stability.

Global Uncertainty Shaping Domestic Decisions

Another important factor behind the MPC’s cautious approach is the uncertain global economic outlook.

The committee warned that geopolitical tensions, energy market disruptions and tighter financial conditions could slow global growth and sustain inflationary pressures across many economies.

Around the world, major central banks are increasingly adopting a cautious and data-driven approach, slowing or pausing monetary easing despite signs of moderating inflation.

The Central Bank of Nigeria appears to be aligning with this global trend by prioritising stability over rapid policy adjustments.

This approach is particularly important for emerging economies like Nigeria, where investor sentiment, exchange rate movements and external financing conditions are highly sensitive to monetary policy signals.

Implications for Nigerians

For ordinary Nigerians, the decision means borrowing costs are likely to remain high in the near term. Commercial bank lending rates may continue to constrain access to affordable credit for businesses and households.

However, the MPC believes maintaining policy discipline is necessary to prevent a return to severe inflationary pressures that could further erode purchasing power and destabilise the economy.

If inflation continues to moderate and exchange rate stability persists over the coming months, the Central Bank of Nigeria may eventually consider gradual monetary easing.

For now, however, the central bank appears determined to consolidate recent macroeconomic gains before making any major policy shift.

The overall message from the MPC meeting is clear: stability remains the priority, and the Central Bank of Nigeria is unwilling to risk reversing the fragile progress achieved through recent reforms.

Salmanu Isah Darazo is a publisher and policy analyst. He can be reached via Salmanudrz@gmail.com