By Salmanu Isah Darazo
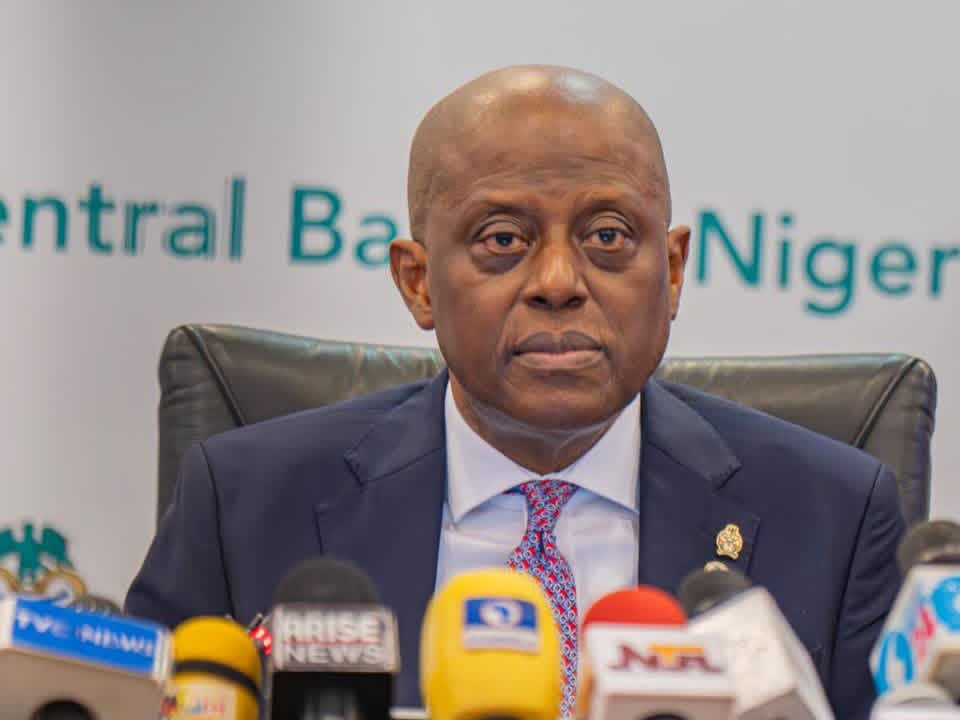
The Central Bank of Nigeria (CBN), is entering another important phase in its monetary-policy reform journey, with the Monetary Policy Committee’s latest decision to reset the Monetary Policy Rate (MPR) at 23 per cent and recalibrate the Standing Facilities Corridor marking a significant operational adjustment in the way monetary policy is transmitted across the Nigerian financial system.
At its 307th meeting held on September 21 and 22, 2026, the MPC approved a corridor of +50/-300 basis points around the MPR, while retaining the Cash Reserve Requirement at 45 per cent for Deposit Money Banks, 16 per cent for Merchant Banks and 75 per cent for non-TSA public-sector deposits. The CBN says the measures are designed to strengthen monetary-policy transmission and reinforce the MPR as the principal signal of monetary policy.
The significance of the decision goes beyond the headline 23 per cent rate. At the heart of the latest move is the CBN’s attempt to correct a structural weakness that had emerged between the official policy rate and prevailing market rates. According to the MPC, this divergence had weakened the effectiveness of monetary-policy transmission. The Bank’s ongoing repair of its monetary-policy implementation framework, including the adoption of the Nigerian Overnight Funding Rate (NOFR) as a transaction-based operational benchmark, is intended to make money-market operations more transparent and ensure that the MPR carries greater influence over financial conditions.
This is therefore less about simply moving an interest-rate number and more about strengthening the machinery through which the CBN implements monetary policy. The Committee was explicit that the corridor recalibration should not be interpreted as a change in the underlying monetary-policy stance. Rather, it described the move as an operational realignment intended to improve transmission and support Nigeria’s transition towards an inflation-targeting framework.
The timing is equally important. The CBN is making this adjustment against the backdrop of improving macroeconomic indicators. Headline inflation fell marginally from 15.43 per cent in July to 15.39 per cent in August 2026, while food inflation declined from 20.31 per cent to 19.57 per cent. Core inflation also fell significantly, from 14.97 per cent to 13.29 per cent. The 12-month moving average of headline inflation has now moderated for 20 consecutive months, according to the MPC.
For the CBN, perhaps more important than the individual monthly figures is the broader direction of travel. The Committee linked the moderation in inflation to the effects of earlier monetary-policy tightening, exchange-rate stability and improved inflation expectations. That assessment suggests that the Bank believes previous policy measures are increasingly feeding through into the wider economy, creating room to concentrate more heavily on improving the efficiency of its policy framework.
The real economy is also providing the CBN with a stronger platform for this recalibration. Nigeria’s real GDP expanded by 4.43 per cent in the second quarter of 2026, compared with 3.89 per cent in the first quarter. Both oil and non-oil sectors recorded stronger performances, while the Purchasing Managers’ Index climbed to 52.7 points in August from 51.1 points in July, pointing to continued expansion in business activity.
Perhaps the strongest evidence of improved external-sector conditions is found in the country’s reserves and balance-of-payments position. Gross external reserves stood at US$55.25 billion as of September 18, 2026—the highest level in 18 years and equivalent to approximately 11.3 months of import cover. Meanwhile, the balance-of-payments surplus increased to US$3.51 billion in the second quarter from US$2.38 billion in the first quarter, while the current-account surplus rose by 67.92 per cent to US$7.54 billion.
Taken together, these indicators explain why the CBN sees sufficient “headroom” for the operational reset. The Bank is effectively trying to consolidate gains already made in inflation, foreign-exchange stability, external reserves and financial-system resilience while making its monetary-policy transmission mechanism more coherent and predictable. The successful recapitalisation of the banking sector, which the MPC says has strengthened capital buffers and banks’ capacity to finance long-term projects, forms another important component of this evolving architecture.
The recalibration also comes at a time when the CBN is placing greater emphasis on coordination between monetary and fiscal authorities. The communiqué highlights the Memorandum of Understanding on fiscal-monetary coordination between the Federal Government, represented by the Ministry of Finance, and the CBN. The stated objective is to provide a structured framework for policy harmonisation towards achieving low and stable inflation.
That coordination could prove particularly important because the CBN’s outlook is not without risks. The Bank identifies prolonged geopolitical tensions in the Middle East, elevated global energy prices and election-related spending as potential sources of renewed inflationary pressure. Globally, growth is projected at 3.0 per cent in 2026, down from 3.5 per cent in 2025, while supply-chain disruptions, commodity-price pressures and trade fragmentation continue to pose risks to the global inflation outlook.
The emerging picture, therefore, is one of a CBN seeking to move from emergency-style monetary tightening towards a more structured and rules-based monetary-policy framework. The 23 per cent MPR is only one part of that story. The deeper story is the effort to ensure that the policy rate actually performs its intended function as the principal monetary-policy signal, with market operations, benchmarks and standing facilities working around it in a more transparent and effective manner.
For Governor Olayemi Cardoso and the CBN, the latest MPC decision consequently represents another chapter in the broader institutional rebuilding of Nigeria’s monetary-policy framework. The immediate challenge will be implementation: whether the recalibrated corridor succeeds in improving transmission without disrupting the disinflation process, while maintaining exchange-rate stability and supporting economic expansion.
The MPC has committed to evaluating the effectiveness of the new corridor and keeping future decisions data-dependent. Its next meeting is scheduled for November 23 and 24, 2026. The direction of monetary policy from that point will provide another important test of whether the current combination of easing inflation, stronger external buffers, expanding output and improved market transmission can be sustained.
Ultimately, the September 2026 decision is best understood not simply as another MPC rate announcement, but as an attempt by the CBN to make Nigeria’s monetary-policy system work more precisely. With inflation moderating, reserves strengthening, output expanding and the financial system undergoing recapitalisation, the Bank is using the present macroeconomic window to recalibrate the machinery of monetary policy—placing the MPR more firmly at the centre of the framework and laying another institutional foundation for a more effective inflation-targeting regime.
Salmanu Isah Darazo is a publisher, analyst and editor. He can be reached via Salmanudrz@gmail.com
CBN’s New Monetary Reset: Recalibrating Policy for a More Stable Nigerian Economy

ByAdmin
23 September 2026